Last Updated -

October 26, 2026

BYD

Company Profile and Market Insights

Explore the business model, global strategy, and market performance including insights into its position in China.

BYD
Key facts
Founded 1995 • Hong Kong: 1211 / Shenzhen: 002594 • H1 2026 results (Jun 30, 2026 period)
RMB344.8b
H1 2026 revenue
RMB13.0b
H1 2026 gross profit
RMB12.3b
H1 2026 profit attributable to owners
RMB1.35
H1 2026 EPS
RMB275.3b
H1 2026 autos & related revenue
RMB941.3b
H1 2026 total assets

About

BYD Company Limited is a Chinese technology and manufacturing group founded in 1995 and headquartered in Shenzhen. The company designs, manufactures and sells new energy vehicles, a category that includes battery electric vehicles and plug-in hybrids. Its portfolio spans mass-market BYD Dynasty and Ocean models, higher-end or specialist brands such as Denza, Fangchengbao and Yangwang, commercial vehicles, rechargeable batteries, energy storage systems, photovoltaics, rail transit and electronics manufacturing services.

‍

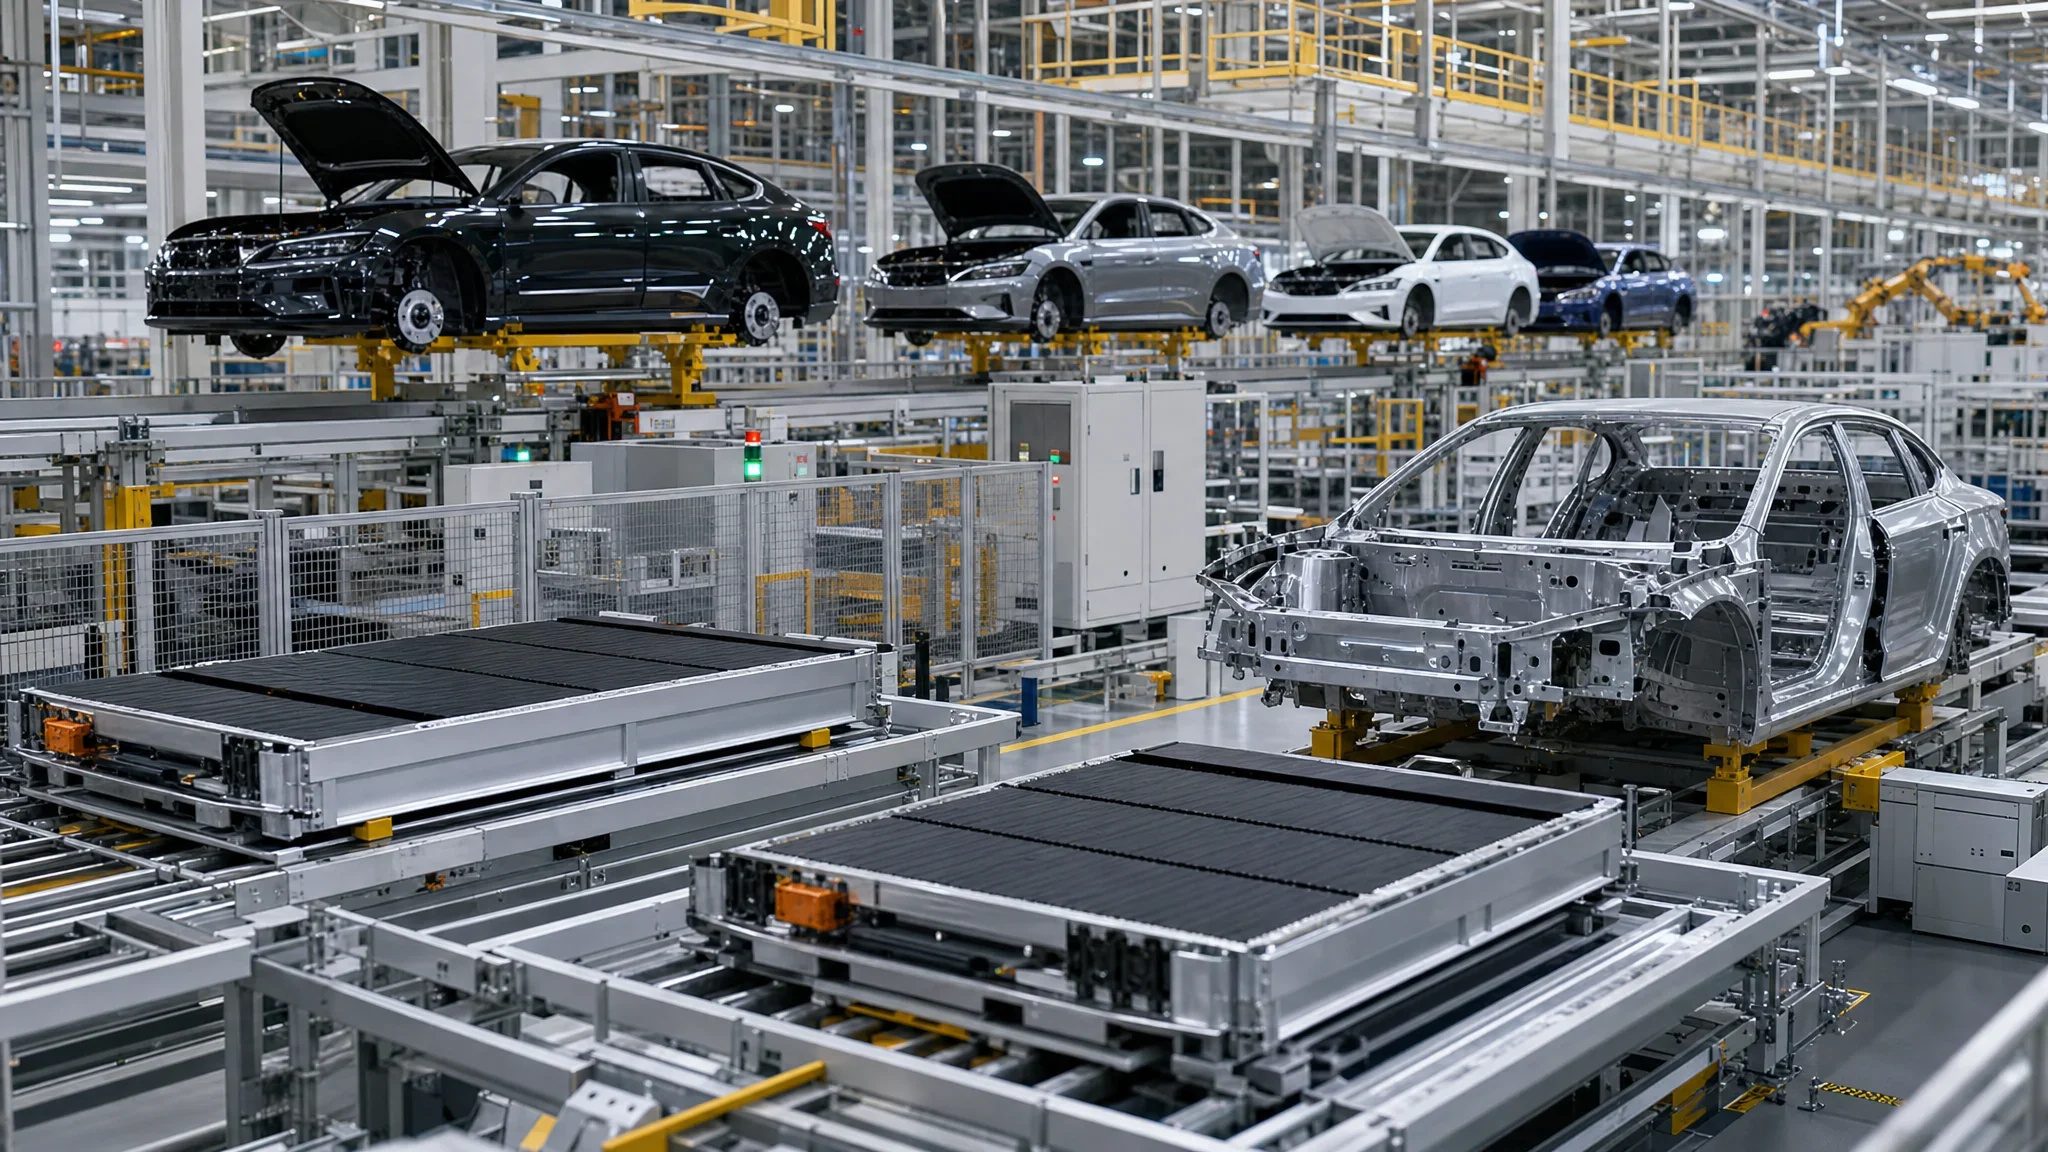
BYD has developed from a battery maker into one of the world’s largest electrified vehicle manufacturers, supported by vertical integration across batteries, power electronics, electric platforms and manufacturing. Its Blade Battery, electrified powertrains and in-house component capabilities help the company control cost, product timing and technology development. The company’s strategic purpose is centered on electrification across energy acquisition, storage and application, with globalization, high-end vehicles and energy storage as important expansion priorities.

‍

In the first half of 2026, BYD reported revenue of RMB344.815 billion, down 7.13% year over year, and profit attributable to owners of the parent of RMB12.325 billion, down 20.54%. Automobiles and related products remained the dominant business at RMB275.341 billion of revenue, while electronics and other products contributed RMB69.405 billion. BYD said it led global new energy vehicle sales and energy storage system shipments in H1 2026, and ranked first in China’s new energy vehicle exports, showing both scale and rising overseas relevance despite earnings pressure in its core market.

BYD

Business Model and Market Position

BYD makes most of its money from designing, manufacturing and selling new energy vehicles, supported by in-house production of batteries, electrified powertrain systems, power electronics and other key components. The company’s model is unusually vertically integrated for a global automaker, which gives it tighter control over cost, supply, product timing and technology differentiation.

‍

In H1 2026, BYD reported revenue of RMB344.815 billion, down 7.13% year over year. Profit attributable to owners of the parent was RMB12.325 billion, down 20.54%, showing that market leadership is being tested by price competition, product mix and demand conditions. Q1 2026 was weaker, with revenue of RMB150.225 billion and attributable net profit of RMB4.085 billion, down 11.82% and 55.38% year over year respectively.

‍

  1. Automobiles and related products: This is BYD’s dominant business, with H1 2026 revenue of RMB275.341 billion, down 8.98% year over year. It includes passenger NEVs, commercial vehicles and related automotive systems.
  2. Electronics and other products: This remains a meaningful second revenue stream, with H1 2026 revenue of RMB69.405 billion, up 0.96% year over year. The segment includes electronics manufacturing services and components for domestic and overseas customers.
  3. Batteries, energy storage and photovoltaics: BYD participates across energy acquisition, storage and application. Its rechargeable battery and energy storage businesses support both internal vehicle production and external energy markets.

‍

BYD’s vehicle portfolio spans mass-market and premium categories. The Dynasty and Ocean series anchor the high-volume passenger vehicle business, while Denza, Fangchengbao and Yangwang target higher-price or specialist segments. This range gives BYD broad exposure across battery electric vehicles, plug-in hybrids, premium SUVs and specialist models.

‍

The company’s main competitive advantage is vertical integration. Proprietary Blade Battery technology, electric platforms, power electronics and in-house manufacturing help BYD compete on cost and product cadence. In March 2026, BYD introduced its second-generation Blade Battery and Flash Charging technology, stating that compatible vehicles were designed to charge from 10% to 70% in 5 minutes and to 97% in 9 minutes under normal-temperature conditions. Its roadmap includes 20,000 Flash Charging stations in China and a global rollout at scale by the end of 2026.

‍

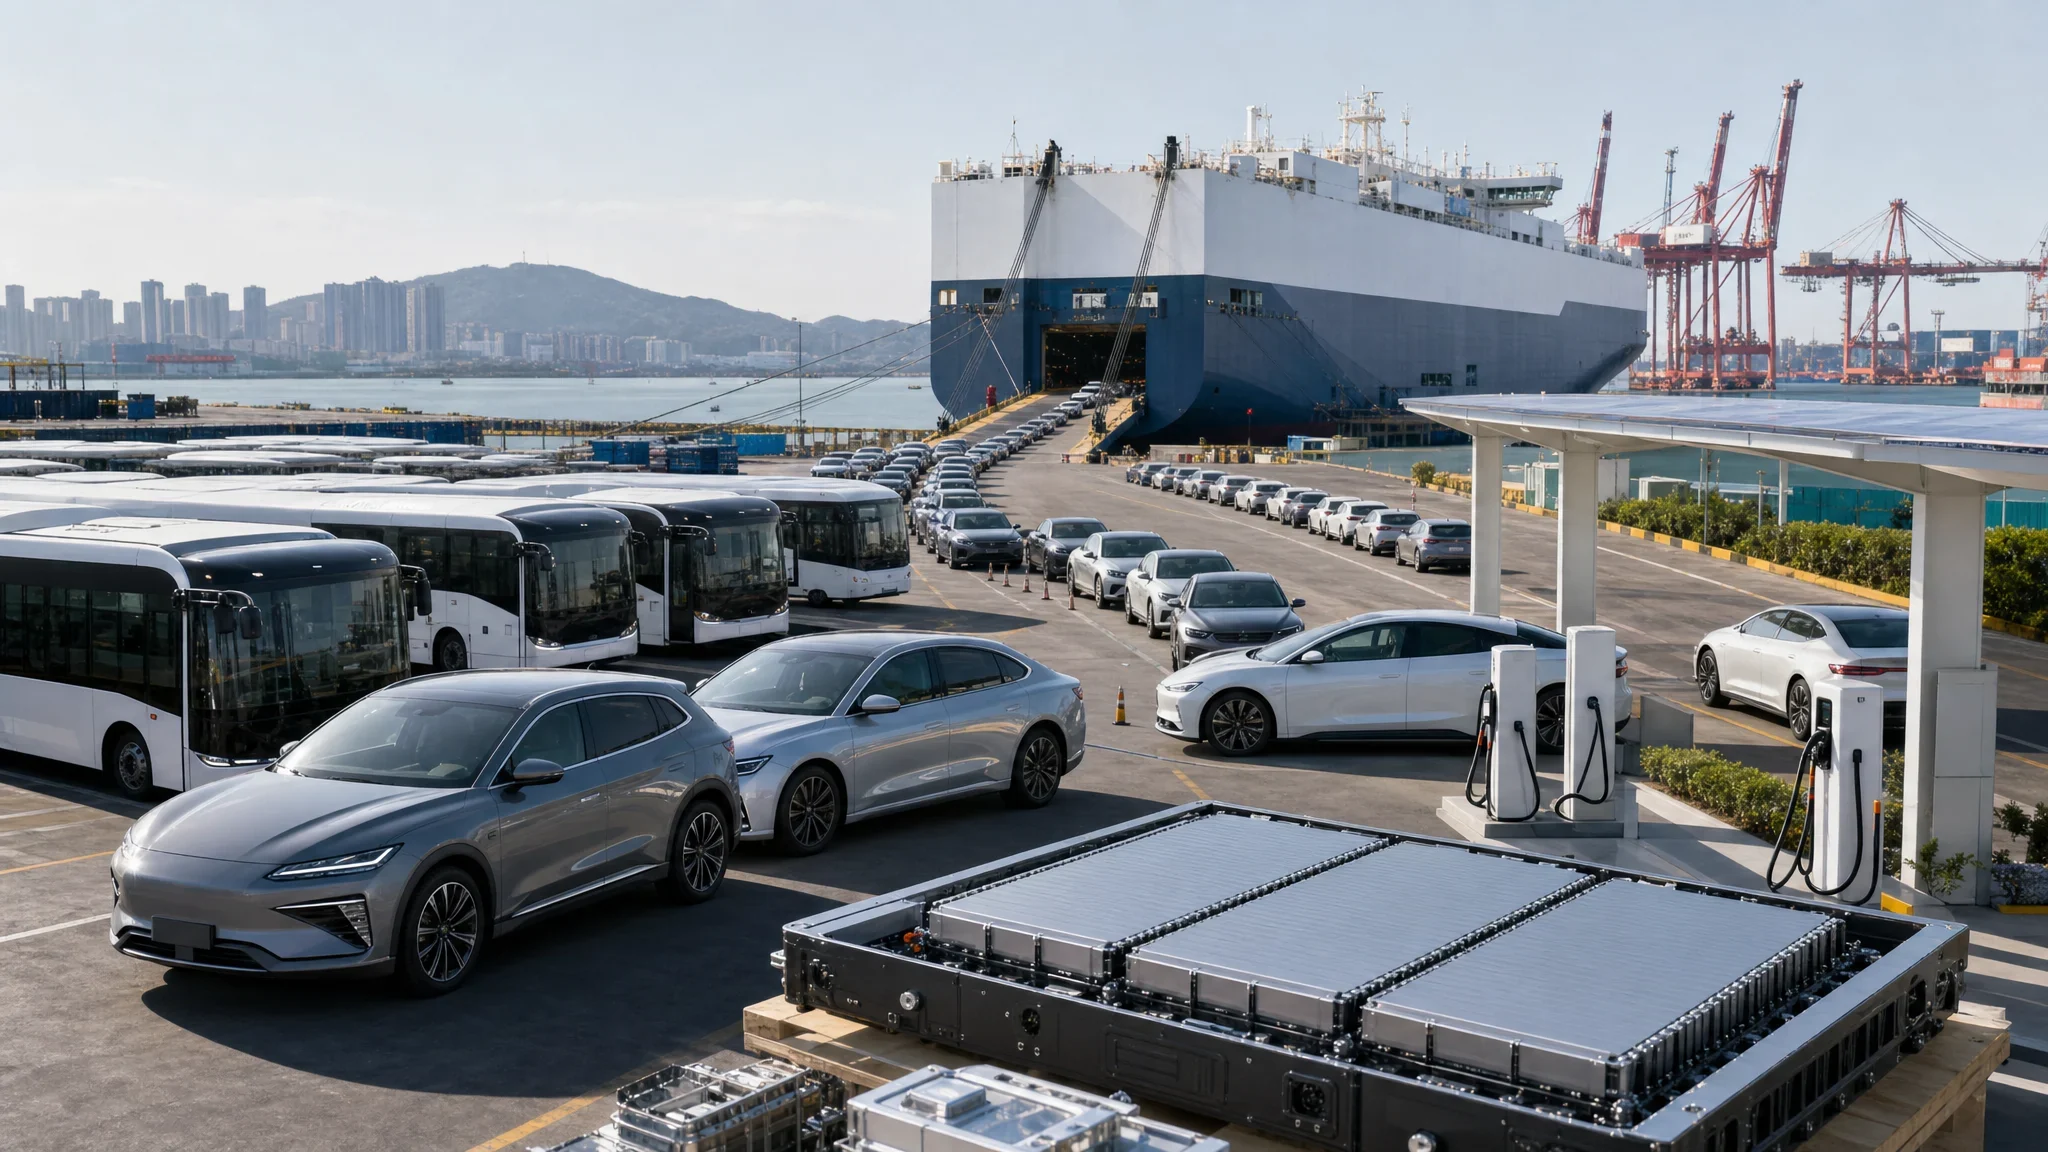
BYD stated that it secured global leadership in both new energy vehicle sales and energy storage system shipments during H1 2026. It also said it ranked first in China’s NEV exports in the period, which indicates that overseas sales are becoming a more important pillar alongside the domestic China market.

‍

China remains central to BYD’s business model. It is the company’s home market, major manufacturing base, R&D base and core competitive arena. Domestic NEV price competition is also a major source of pressure, which is visible in the H1 2026 decline in earnings despite BYD’s scale advantages.

‍

International expansion is becoming more important. BYD is accelerating overseas localization, including planned European production in Hungary and battery and manufacturing expansion in Brazil. Local production supports market access, reduces tariff exposure and helps the company compete outside China with a more localized cost and supply base.

‍

BYD’s closest global comparison is Tesla in battery electric vehicles, but BYD has a broader NEV mix because it sells substantial plug-in hybrid volumes in addition to battery electric vehicles. Tesla remains a direct global competitor in EV technology, pricing and brand positioning, while BYD’s China and global competitors also include Geely, SAIC, Li Auto, XPeng, NIO and other Chinese and international automakers.

‍

BYD’s market position is strong because it combines scale, battery expertise, vehicle breadth, energy storage exposure and a growing export base. The key investor issue is whether those strengths translate into resilient margins as China’s NEV market stays highly competitive and overseas expansion requires investment in factories, distribution, service networks and localized supply chains.

BYD

Performance in China

China is BYD’s home market and remains central to its revenue, manufacturing, R&D, supply chain and competitive position. In H1 2026, BYD reported revenue of RMB344.815 billion, down 7.13% year over year, with automobiles and related products contributing RMB275.341 billion. Q1 2026 revenue fell 11.82% to RMB150.225 billion, while attributable net profit dropped 55.38% to RMB4.085 billion, showing pressure from China’s intense NEV price competition and demand volatility. BYD’s local strategy combines vertical integration, rapid model refreshes across Dynasty and Ocean, premium expansion through Denza, Fangchengbao and Yangwang, and deeper control of charging infrastructure. In March 2026, it introduced second-generation Blade Battery and Flash Charging technology, with a roadmap for 20,000 Flash Charging stations in China. Main competitors include Tesla, Geely, SAIC, Li Auto, XPeng, NIO and other domestic NEV makers.

Growth and Future Prospects

BYD enters the next phase of growth from a position of scale, but its latest results show that expansion is coming with lower near-term profitability. In H1 2026, revenue fell 7.13% year over year to RMB344.815 billion, while profit attributable to owners of the parent fell 20.54% to RMB12.325 billion. Q1 2026 was weaker, with revenue down 11.82% and attributable net profit down 55.38%. The turning point for investors is that BYD remains a global leader in new energy vehicles and energy storage, yet domestic price competition and overseas investment are pressuring earnings.

‍

Key growth drivers

‍

  1. Overseas expansion: BYD is scaling exports and local production in markets including Europe and Brazil. Planned assembly in Hungary and battery and manufacturing expansion in Brazil support localization, which helps reduce tariff and local-content risks.
  2. Product expansion: The company is widening its range across mass-market BYD Dynasty and Ocean models, higher-end Denza, Fangchengbao and Yangwang vehicles, commercial vehicles, batteries, energy storage and electronics manufacturing.
  3. Technology cycle: BYD’s second-generation Blade Battery and Flash Charging technology are intended to improve charging speed and product competitiveness. The company has outlined a plan for 20,000 Flash Charging stations in China, with broader global rollout targeted by the end of 2026.
  4. Energy storage and electronics: BYD reported global leadership in energy storage system shipments in H1 2026. Its electronics segment also remained more stable than autos, with H1 2026 revenue up 0.96%, and is moving into areas such as AI computing infrastructure.

‍

Challenges ahead

‍

  1. Margin pressure: China’s NEV price war remains the central risk, especially because China is still BYD’s core sales, manufacturing and policy market.
  2. Execution risk: Overseas factories, distribution, service networks and supply chains require capital and management attention.
  3. Trade and geopolitical exposure: Tariffs, security reviews and consumer perceptions of Chinese brands affect global expansion.
  4. Inventory and cash flow: Rising inventory and weaker Q1 operating cash flow increase risk if demand softens or product cycles shorten.

‍

BYD’s outlook is mixed but strategically strong. The company has clear growth paths in exports, localized manufacturing, premium vehicles, energy storage and charging infrastructure. The investment case depends on whether these initiatives restore earnings growth after the H1 2026 downturn, rather than only adding volume.

Next Earnings Planned for:

October 29, 2026

This Company Profile was written by Dominik Diemer

Dominik Diemer blends an investor mindset with execution discipline.

He is a SAFe Program Consultant (SPC) and Lean Portfolio Management (LPM) practitioner at DMG MORI Digital, working as a SAFe Release Train Engineer and internal consultant in the Lean-Agile Center of Excellence (LACE).

His focus is prioritization, flow, and dependency management that turns strategy into outcomes. With experience across Bertelsmann and the Founders Foundation, he bridges corporate and startup thinking.

He also invests privately in private equity deals, sharpening his view on business models, value drivers, and go-to-market.

StockCounterParts reflects that lens.