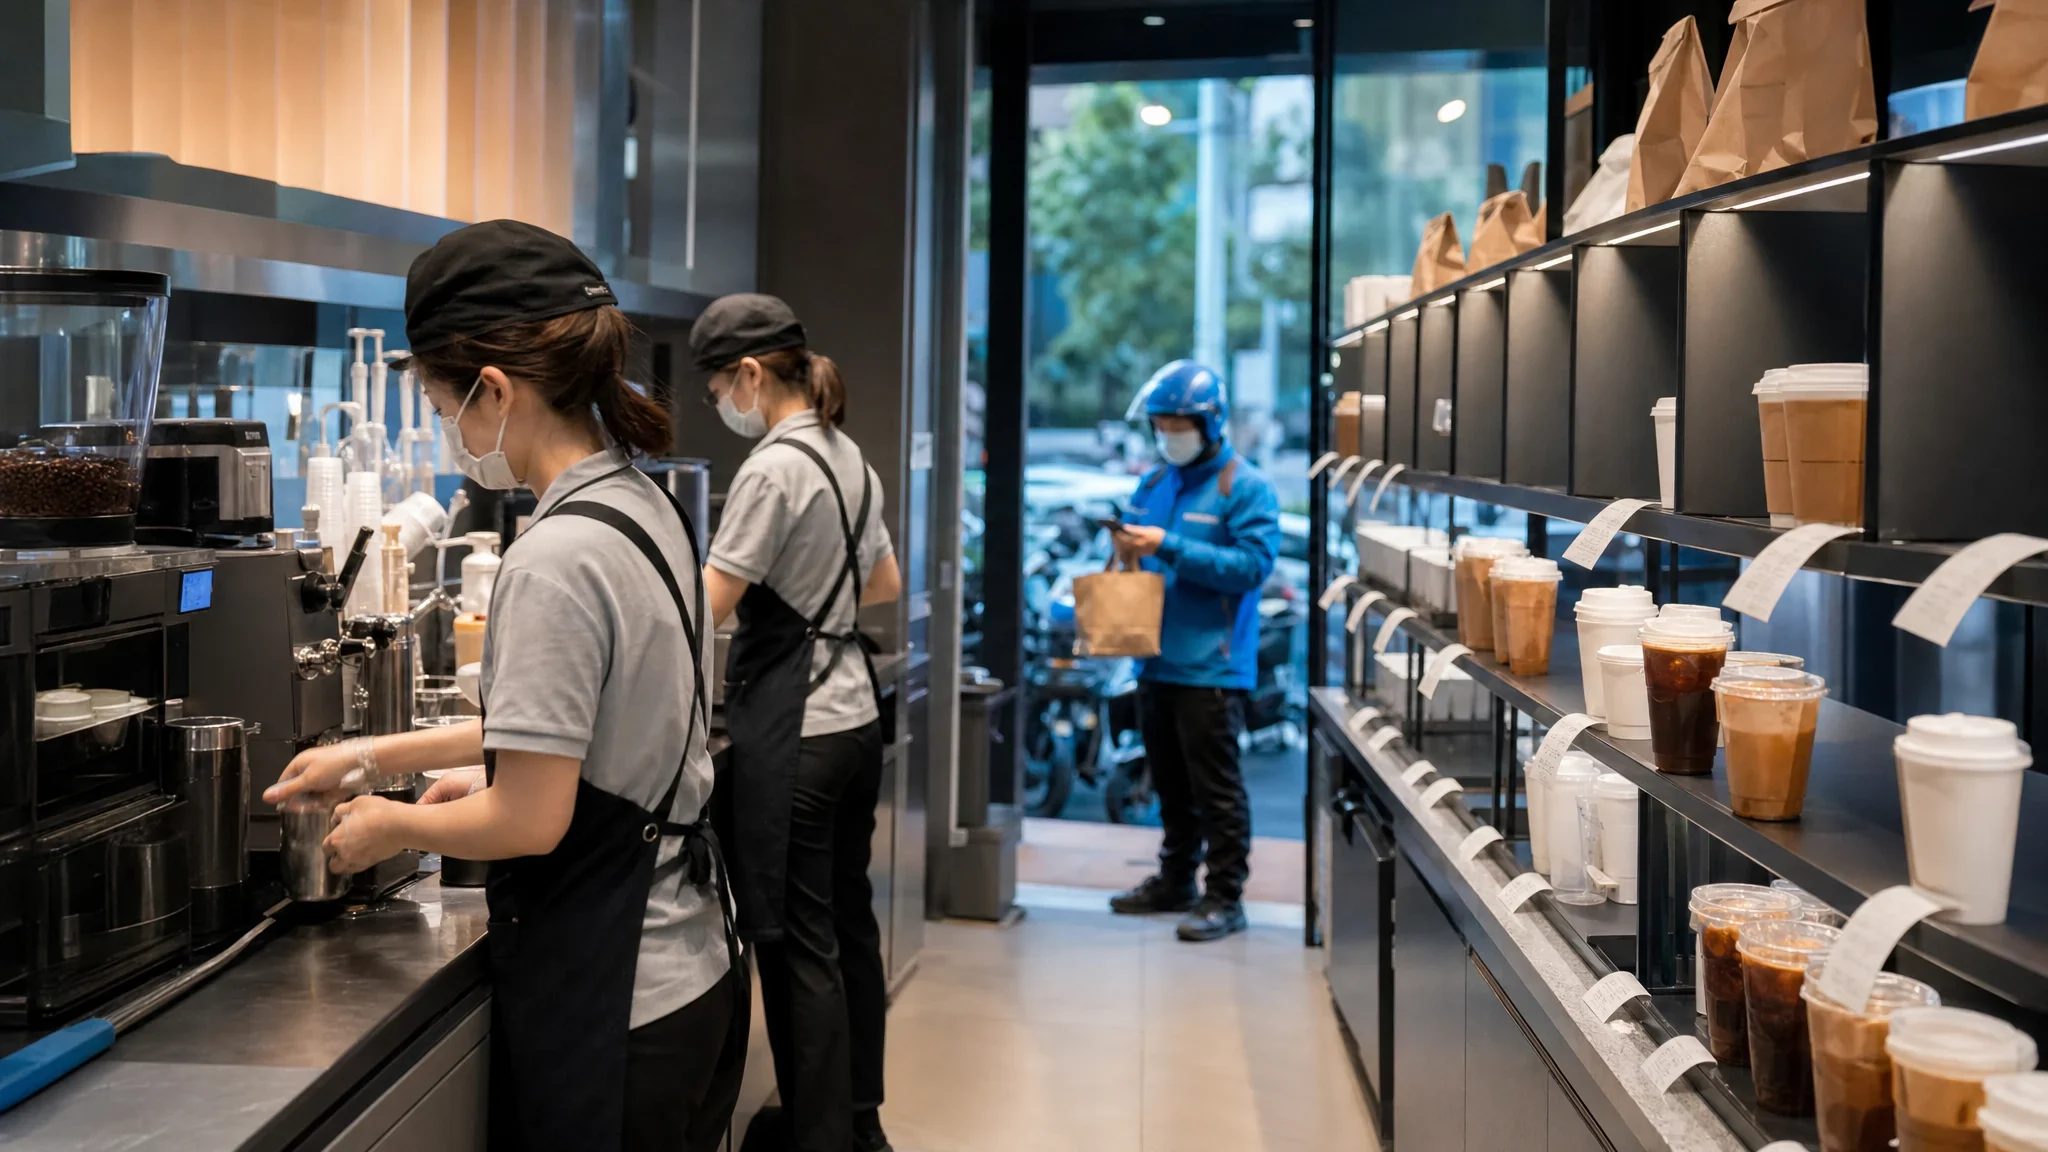
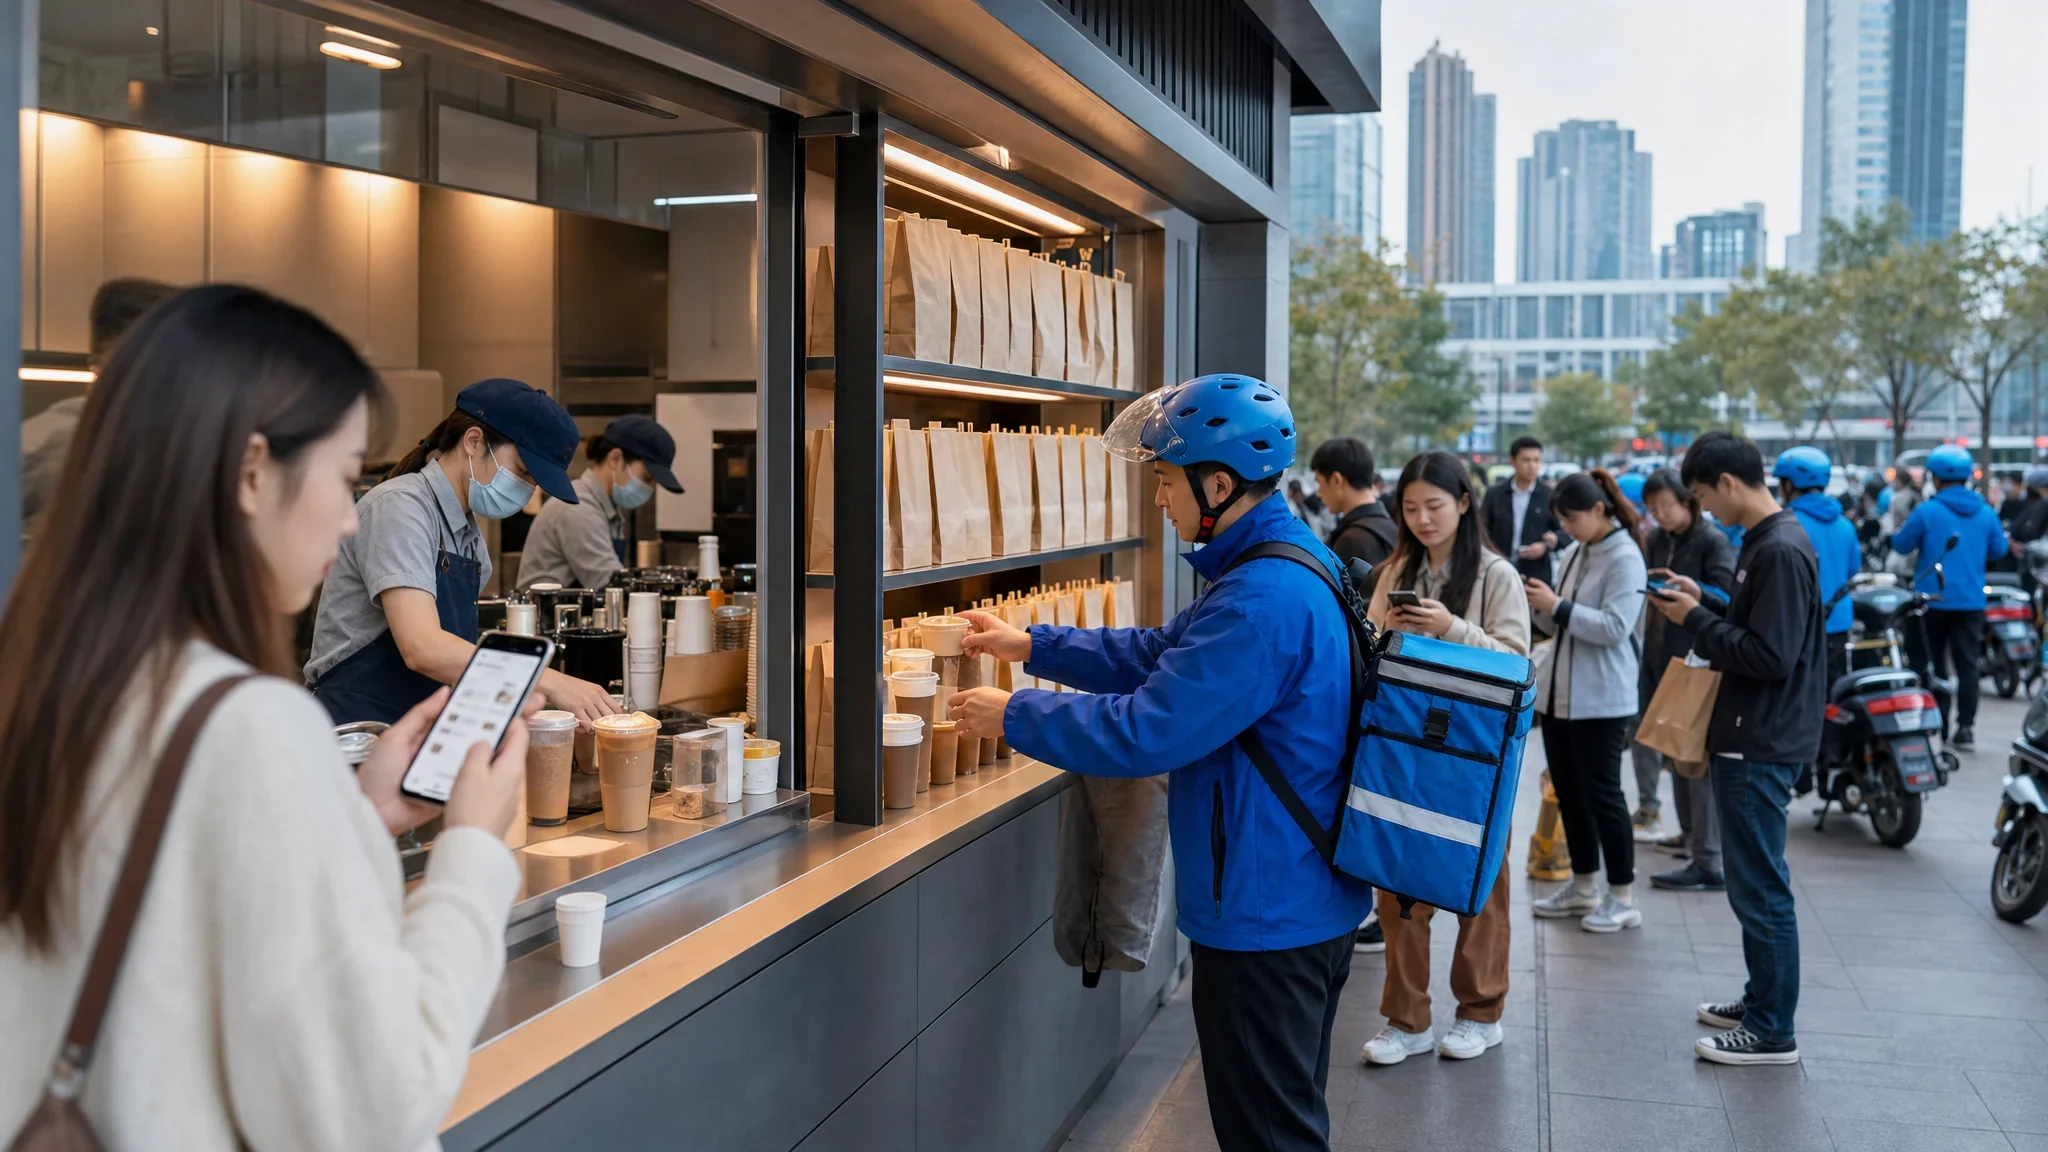
Luckin Coffee makes money by selling freshly made coffee and other beverages through a large, app-led store network, mainly in China. Its model combines self-operated stores, where Luckin controls retail sales directly, with partnership stores, which extend the network while generating revenue from materials, equipment, delivery services, profit sharing, royalties, franchise fees and other services.
In Q2 2026, Luckin reported total net revenue of RMB15.89 billion, up 28.5% year over year. Self-operated store revenue was RMB11.56 billion, while partnership-store revenue was RMB3.67 billion. Freshly brewed drinks remained the core product category, contributing RMB11.15 billion, or about 70.2% of total net revenue. Non-coffee beverages have become a meaningful extension, with cumulative sales above RMB20 billion as of May 31, 2026.
The company’s operating model is built around mobile ordering, third-party platform integration, cashier-less transactions, pickup stores, delivery and data-driven operations. Store formats include pickup stores and relax stores, with pickup stores supporting high density, convenience and lower-service retail occasions. This differs from a traditional café-led model by emphasizing throughput, app-based customer acquisition and affordable daily consumption.
Key revenue streams are
- Self-operated stores: Direct sales of freshly brewed drinks, other products, e-commerce items, offline sales and delivery revenue.
- Partnership stores: Materials, equipment, delivery services, profit sharing, royalty fees, franchise fees and other services.
- Product categories: Coffee drinks, non-coffee beverages and other retail products sold through stores and digital channels.
Luckin’s main operating advantages are scale, convenience and digital execution. At June 30, 2026, the company had 36,310 stores globally, including 23,734 self-operated stores and 12,576 partnership stores. Its average monthly transacting customers reached 112.7 million in Q2 2026, a company record and a sign of broad mass-market reach. Scale also supports procurement, supply-chain planning, menu testing and rapid product rollout.
China remains the core market. Of the 2,714 net new stores opened in Q2 2026, 2,668 were in China including Hong Kong. International operations are still smaller, though Singapore has become the clearest overseas proof point. Luckin opened its 100th Singapore store in September 2026 and described itself as the second-largest coffee chain there by store count.
Luckin competes with Starbucks China, Cotti Coffee, convenience-store coffee, tea chains, delivery-platform beverage sellers and other quick-service drink brands. Compared with Starbucks, Luckin is positioned around lower price points, smaller pickup-focused stores, mobile-first ordering and denser network expansion. Starbucks remains a major premium café peer, while Luckin targets frequent, convenient and affordable consumption.
Luckin is one of China’s largest coffee chain brands by store count and has built a leading position in the country’s mass-market coffee segment. The main challenge is maintaining store productivity and margins while expanding quickly. In Q2 2026, self-operated same-store sales growth was negative 5.3%, compared with positive 13.8% a year earlier, which points to pressure from promotions, competition or a difficult comparison base even as total revenue and customer numbers continue to grow.