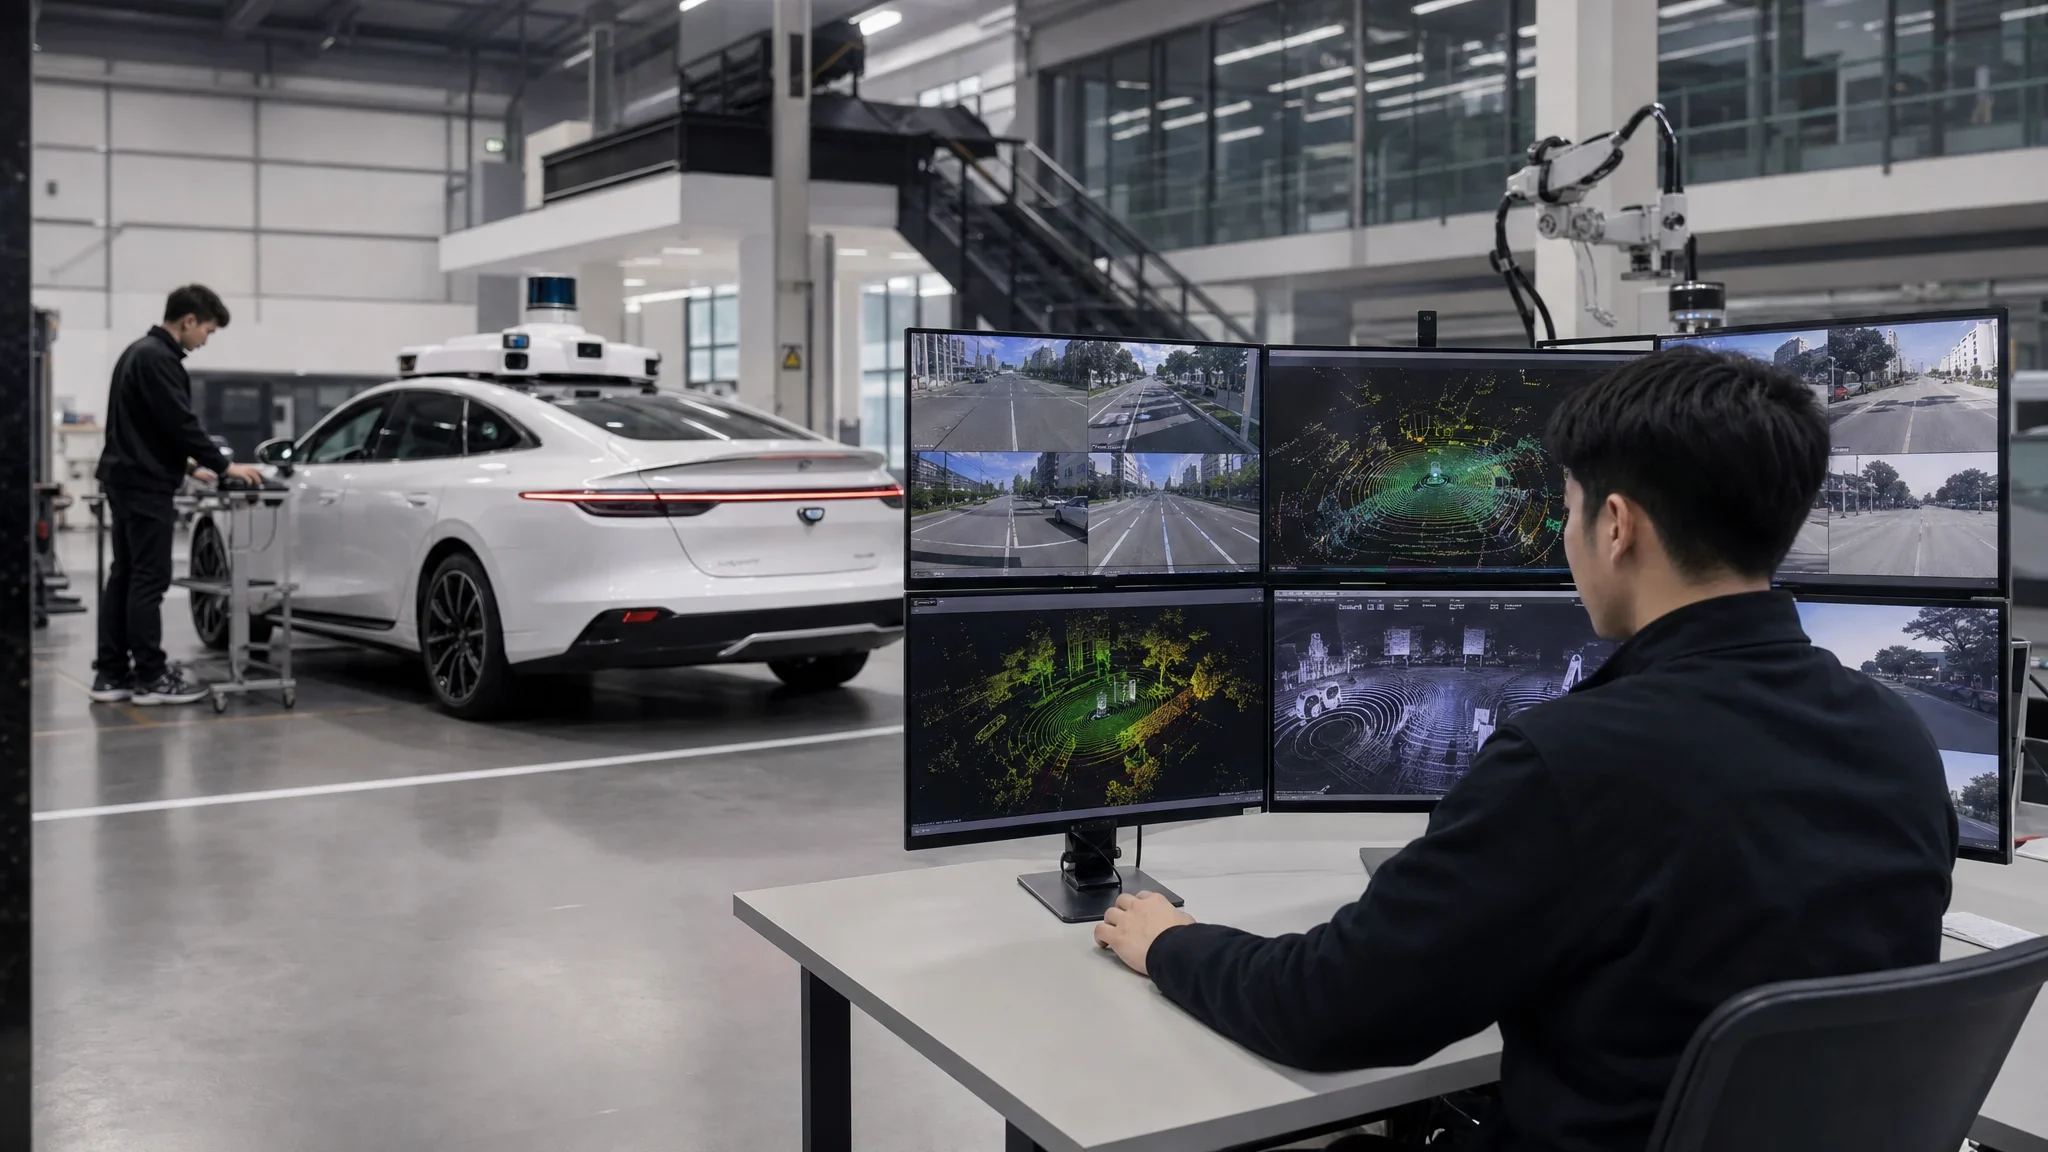
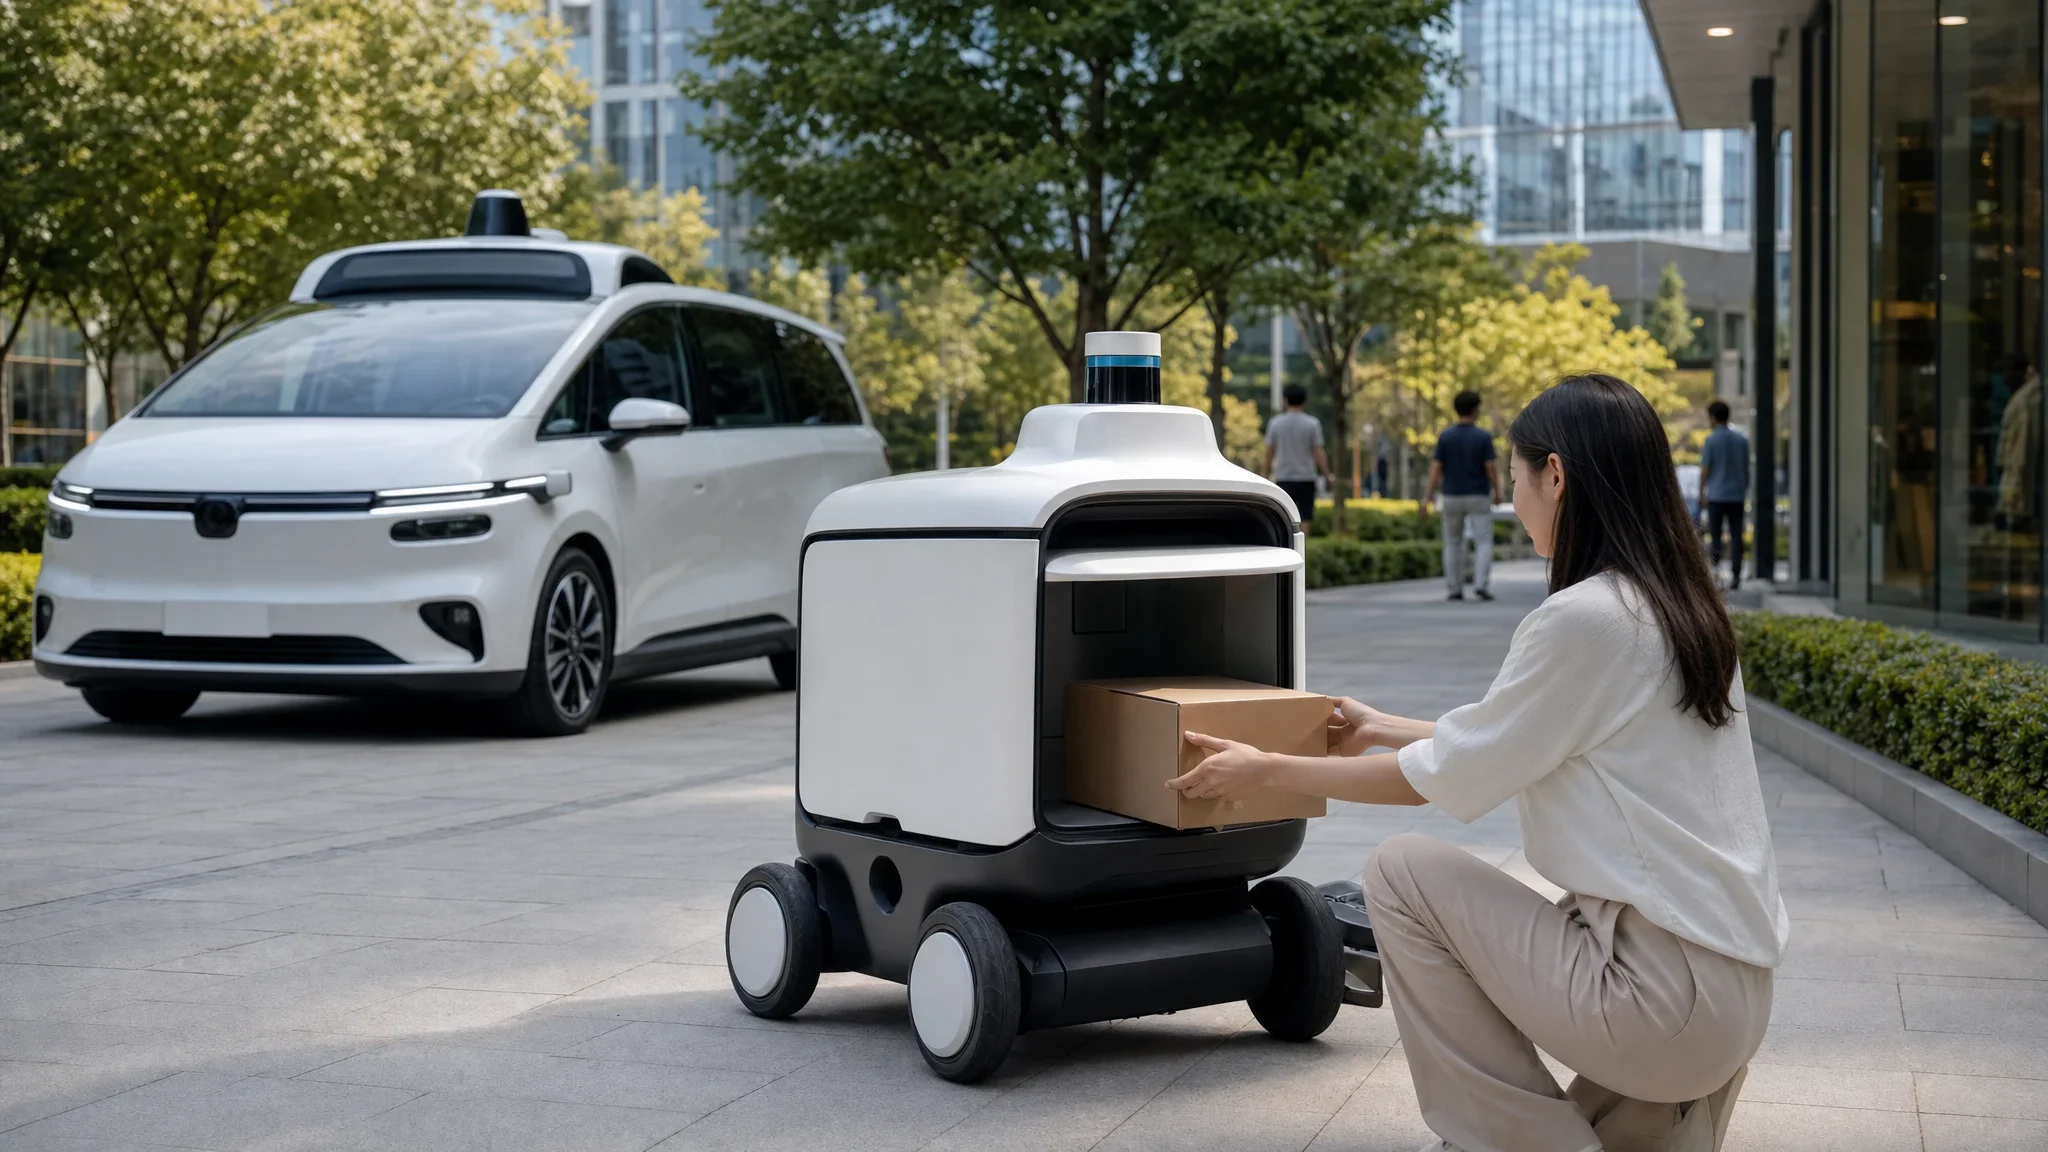
Pony AI develops and commercializes Level 4 autonomous driving technology. Its business model combines fleet-based mobility services, autonomous freight services, and sales of autonomous-driving systems to automakers and mobility partners. The company is still in the investment phase, with rapid revenue growth offset by heavy spending on R&D, vehicle deployment, data centers, servers, and commercialization.
In Q2 2026, Pony AI generated US$36.2 million of revenue, up 68.8% year over year. Gross profit was US$6.4 million, with a 17.5% gross margin. The company remained loss-making, with a Q2 2026 operating loss of US$65.7 million and a net loss of US$45.4 million. Liquidity-like resources totaled US$1.39 billion at June 30, 2026, giving the company funding capacity as it scales an asset-intensive autonomous fleet model.
Pony AI reports three main revenue streams
- Robotaxi services: This is the company’s flagship business. Revenue comes from fare-charging rides and vehicle deployment under joint deployment models with partners. Q2 2026 robotaxi services revenue was US$12.1 million, up 691.2% year over year, with fare-charging revenue rising more than 800%. Growth was driven by the Gen-7 fleet launch, commercial expansion, and higher joint-deployment revenue.
- Robotruck services: Pony AI provides autonomous and intelligent trucking and freight transportation services, including collaboration with Sinotrans and deployment in logistics settings such as ports and highways. Q2 2026 robotruck services revenue was US$13.3 million, up 40.0% year over year. The segment supports the company’s effort to apply its autonomous-driving stack to commercial freight, where repeatable routes and logistics partners create a different route to scale than consumer ride-hailing.
- Intelligent solutions: Pony AI sells autonomous-driving products and services to OEMs and ecosystem partners. Products include autonomous domain controllers, software, engineering solutions, and AV hardware kits. Q2 2026 intelligent solutions revenue was US$10.8 million, broadly flat year over year, as deliveries of autonomous domain controllers fluctuated.
For the first half of 2026, total revenue was US$70.5 million. Robotaxi services contributed US$20.6 million, robotruck services contributed US$23.5 million, and intelligent solutions contributed US$26.3 million. This mix shows that Pony AI is still diversified across commercialization paths, even as robotaxi growth is becoming more prominent.
Pony AI’s operating strategy depends on mass-produced autonomous vehicle platforms from OEM partners and joint deployment models that reduce the burden of fully self-funded fleet expansion. In China, the company has a joint venture with Toyota and GTMC for robotaxi mass production and large-scale deployment, and it has worked with OEMs including BAIC, GAC, and SAIC. The company also distributes robotaxi access through local consumer channels such as PonyPilot, WeChat mini programs, Amap, WeChat mobility services, and Alipay mini programs.
The company’s main competitive advantages are
- Commercial operating footprint: Pony AI says it is among a select group of companies with fully driverless commercial operations and large-scale autonomous-driving commercialization capability.
- China Tier-1 city licenses: The company says it was among the first in China to secure licenses for fully driverless robotaxi operations across Beijing, Shanghai, Guangzhou, and Shenzhen.
- Scaling fleet base: Pony AI operated 1,975 robotaxis as of June 30, 2026, up from more than 1,400 at March 31, 2026. Management continued to target more than 3,500 robotaxis by the end of 2026.
- Technology platform: PonyWorld and Virtual Driver form the core autonomous-driving stack across robotaxi, robotruck, and intelligent-solutions products, giving the company a common technology base across multiple use cases.
- Partner-led expansion: The company is expanding through partners in China and overseas, including collaborations tied to Europe, Singapore, Croatia, Qatar, Kazakhstan, and other markets.
China is Pony AI’s core market. Its earliest and largest robotaxi commercialization base is in Chinese Tier-1 cities, and its robotruck activity includes freight operations across China, Sinotrans collaboration, and Gen-4 driverless robotruck deployment at Mawan Port in Shenzhen with China Merchants Port. This gives Pony AI strong exposure to one of the world’s largest mobility markets, while also making permits, city-level rules, data regulation, road-safety oversight, and PRC regulatory policy central to the investment case.
Pony AI competes with WeRide, Baidu Apollo, Waymo, and other robotaxi and autonomous trucking platforms. WeRide is the closest public-market peer for investors comparing China-based autonomous-driving commercialization. Waymo is the most relevant global benchmark in driverless robotaxi operations, especially in the United States, although Pony AI’s model is more China-centered and includes a broader reported mix of robotaxi, robotruck, and intelligent-solutions revenue.
Pony AI’s market position is that of a leading China-based autonomous mobility company moving from pilots toward larger commercial deployment. The robotaxi fleet reached 1,975 vehicles by the end of Q2 2026, and the company had reported more than 65.0 million cumulative autonomous-driving kilometers as of March 31, 2026. Its 2025 annual report also noted city-wide unit economics breakeven in Guangzhou in November 2025 and Shenzhen in February 2026 for the robotaxi business, an important operating milestone, though not the same as corporate profitability.
The main investor question is whether Pony AI turns technical leadership and regulatory access into profitable scale. Revenue growth, fleet expansion, and international partnerships show commercial traction. At the same time, the business remains capital intensive, with Q2 2026 capital expenditures of US$32.2 million and continuing losses. Its market position is strong among autonomous-driving challengers, but sustained advantage will depend on safety performance, utilization density, regulatory approvals, partner execution, and improved unit economics across more cities.